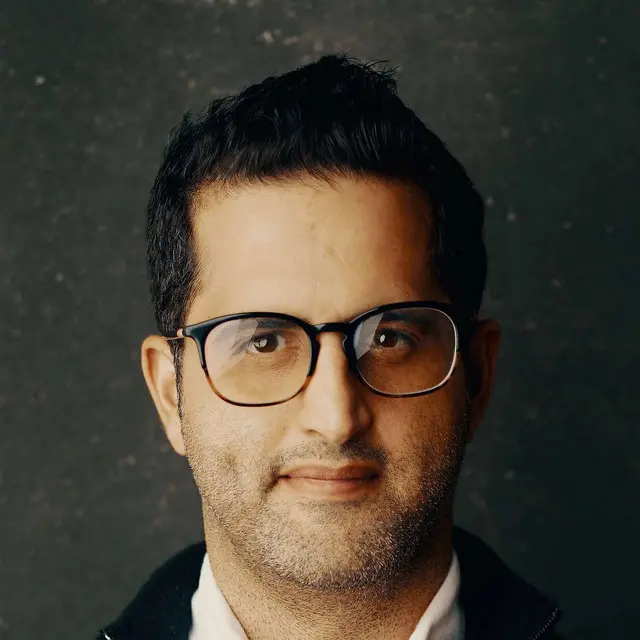
Bam Azizi of Mesh, chief executive officer and cofounder, discusses securing real-time financial rails and tokenized payments at theCUBE and New York Stock Exchange Wired: Mixture of Experts. Azizi brings expertise in security, identity and crypto infrastructure and traces a career from passwordless identity to founding Mesh to simplify financial rails. They emphasize practical approaches to scaling secure payment systems.
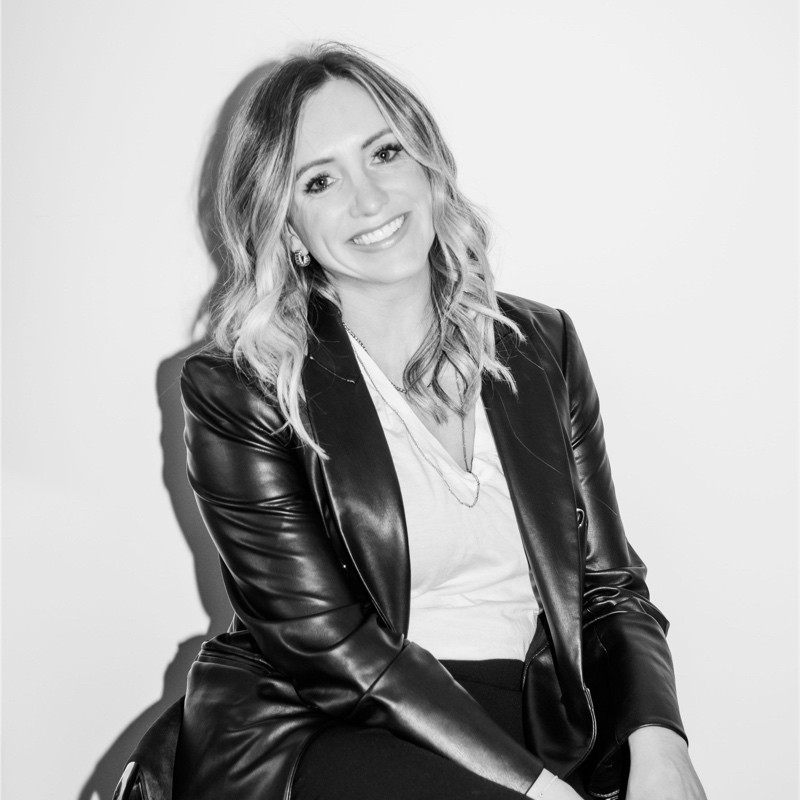
This conversation with host Gemma Allen of theCUBE Research explores tokenized payments, stablecoins, decentralized identity, agentic artificial intelligence AI and the technical challenges of integrating exchanges, wallets and regulatory frameworks to enable seamless global money movement.
Key takeaways include Mesh's focus on B2B2C consumer payments and a security-first pass-through architecture that minimizes stored data, according to Azizi. They frame stablecoins as an immediate payment rail and project a tokenized economy opportunity on the order of US$100 trillion. theCUBE hosts also highlight the strategic stickiness of infrastructure that abstracts fragmentation across chains and payment networks.
Topics covered include payments, tokenization, stablecoins, decentralized identity, security, crypto infrastructure, exchanges, wallets, regulatory frameworks and agentic AI. Subscribe for further discussions on payments infrastructure, crypto payments and digital asset interoperability.
Forgot Password
Almost there!
We just sent you a verification email. Please verify your account to gain access to
theCUBE + NYSE Wired: Mixture of Experts Series. If you don’t think you received an email check your
spam folder.
Sign in to theCUBE + NYSE Wired: Mixture of Experts Series.
In order to sign in, enter the email address you used to registered for the event. Once completed, you will receive an email with a verification link. Open this link to automatically sign into the site.
Register For theCUBE + NYSE Wired: Mixture of Experts Series
Please fill out the information below. You will recieve an email with a verification link confirming your registration. Click the link to automatically sign into the site.
You’re almost there!
We just sent you a verification email. Please click the verification button in the email. Once your email address is verified, you will have full access to all event content for theCUBE + NYSE Wired: Mixture of Experts Series.
I want my badge and interests to be visible to all attendees.
Checking this box will display your presense on the attendees list, view your profile and allow other attendees to contact you via 1-1 chat. Read the Privacy Policy. At any time, you can choose to disable this preference.
Select your Interests!
add
Upload your photo
Uploading..
OR
Connect via Twitter
Connect via Linkedin
EDIT PASSWORD
Share
Forgot Password
Almost there!
We just sent you a verification email. Please verify your account to gain access to
theCUBE + NYSE Wired: Mixture of Experts Series. If you don’t think you received an email check your
spam folder.
Sign in to theCUBE + NYSE Wired: Mixture of Experts Series.
In order to sign in, enter the email address you used to registered for the event. Once completed, you will receive an email with a verification link. Open this link to automatically sign into the site.
Sign in to gain access to theCUBE + NYSE Wired: Mixture of Experts Series
Please sign in with LinkedIn to continue to theCUBE + NYSE Wired: Mixture of Experts Series. Signing in with LinkedIn ensures a professional environment.
Are you sure you want to remove access rights for this user?
Details
Manage Access
email address
Community Invitation
Bam Azizi, Mesh
Bam Azizi of Mesh, chief executive officer and cofounder, discusses securing real-time financial rails and tokenized payments at theCUBE and New York Stock Exchange Wired: Mixture of Experts. Azizi brings expertise in security, identity and crypto infrastructure and traces a career from passwordless identity to founding Mesh to simplify financial rails. They emphasize practical approaches to scaling secure payment systems.
This conversation with host Gemma Allen of theCUBE Research explores tokenized payments, stablecoins, decentralized identity, agentic artificial intelligence AI and the technical challenges of integrating exchanges, wallets and regulatory frameworks to enable seamless global money movement.
Key takeaways include Mesh's focus on B2B2C consumer payments and a security-first pass-through architecture that minimizes stored data, according to Azizi. They frame stablecoins as an immediate payment rail and project a tokenized economy opportunity on the order of US$100 trillion. theCUBE hosts also highlight the strategic stickiness of infrastructure that abstracts fragmentation across chains and payment networks.
Topics covered include payments, tokenization, stablecoins, decentralized identity, security, crypto infrastructure, exchanges, wallets, regulatory frameworks and agentic AI. Subscribe for further discussions on payments infrastructure, crypto payments and digital asset interoperability.
>> (INTRO)Welcome back to theCUBE Studio here at the New York Stock Exchange. I'm Gemma Allen, co-host of NYSE Wired's Mixture of Experts. And joining me now for a conversation is Bam Azizi, who has spent his career solving one problem, and that is how do you make complicated technology disappear for the person using it? He went from passwordless identity with NoPassword to crypto infrastructure with Mesh. And now the conversation is moving towards something even bigger and more real time. And that is, can we build financial rails that let humans, companies, and eventually agents if not already, move money seamlessly. Bam, CEO and co-founder of Mesh. Welcome to NYSE Wired.
Bam Azizi
>> Thank you for having me. Super excited for the conversation.
Gemma Allen
>> So maybe help me unpack some of what I said there in my opening. Bring this story to life for some of our listeners and viewers. This is an interesting space you're in. It's essentially about securing the financial rails of the future. It's a company that has, I guess, had multiple inflection points. Give us the backstory here, Bam. Help us understand exactly who Mesh is and how you guys got here.
Bam Azizi
>> Yeah, so Mesh, we only have one mission, it's just making it simple. The joke is crypto is built by crypto bros for crypto bros, and we want to kind of simplify that so the mainstream can use that. I use the analogy of like the grandma, you want the grandma to be able to go to a coffee shop and then pay with crypto. Sometimes they don't even know the merchant or the end users even don't know that they're paying with crypto. So the actual settlement happens on crypto blockchain, which is fast, global and kind of instant and also very, very cheap. That's kind of our mission. It's very, very hard to do that. It's easier said than done because you have to basically integrate with hundreds of different exchanges and wallets in different countries, different currencies. To be able to offer simple, one line of code. And I would compare us to what Stripe did for credit card. Earlier on, you had to build a whole stack to be able to offer payment processing. Same thing goes to crypto processing. So you want to kind of make it simpler for end users. And as you mentioned, the next generation of consumers are not going to be humans, they're going to be agents. So I want to kind of make it simpler for them too.
Gemma Allen
>> So if we think about the kind of original thesis of Mesh, which is somewhat of the original thesis of the crypto industry broadly, and that is that a lot of folks had crypto spread across different places, right? And that experience kind of sucked in a way, right? And it was also a little bit obvious from the fact that you could have Coinbase, you could have wallets or exchanges, and you didn't really have connective tissue, per se. We saw the rise of institutionalization, and the kind of meeting of Wall Street and the crypto bros and the demands for a certain level of I suppose, housekeeping and security that those things naturally brought. And now almost before that was even solved, or at least that narrative was solved. Now we're talking about the world of agentic AI. So from the perspective of the tech that you guys are building, are you building one solution for everything, or how multifaceted is this space when we combine, like I said, blockchain and the world of agentic AI?
Bam Azizi
>> Yeah, we want to make money movement simple, whether it's B2B payment or P2P payment, peer-to-peer, or consumer-to-consumer, you name it. So we want to make it as easy as possible. If you look at it historically, there were different networks for different types of use cases. For instance, you would use ACH or wire for domestic. You would use international wire if you want to send money cross-border. You would use Visa or Mastercard if you want to pay for something, right? So there are different types of networks for different types of use cases. But blockchain came in, so you don't need any intermediary. So one person can pay another one as long as they both have access to the internet. On top of that, you basically don't need different networks. You just need one network that can move assets, tokenize assets from point A to point B. The caveat is we don't have only one blockchain. We have thousands of different tokens, different blockchains, different currencies. So it's very, very fragmented. So it's going to be a $100 trillion market cap, not because Bitcoin price is going up, it's because you're bringing all these real-world assets on-chain. But the caveat is it's very, very sophisticated technology and it's a very challenging environment for businesses and end users to use. So that's where Mesh comes in and abstracts all of the complexity and makes it as simple as possible for end users and businesses to move money for different types of use cases. And if the next generation of users are agents, we want to kind of make it simple and possible for them to interact and transact globally and instantly.
Gemma Allen
>> So talk about the TAM that you guys are chasing because it's again quite varied, right? You guys are working with companies like PayPal, which is more of a mainstream consumer product for the most part. At least that's how I would understand it. Maybe the folks at PayPal would disagree. But also institutions. And there's kind of a different vibe across that industry, right? Especially as we think about the world of payments. Help me understand, like, where is the largest TAM right now for a company like Mesh? And where are you guys truly focusing? Or are you focusing on a little bit of everything, which is what some folks say?
Bam Azizi
>> Yeah. So Mesh is making money movement simple. So you can apply that logic for different types of use cases. As I mentioned, right now we are focused mostly on consumer payments. So we do a lot of B2B2C. So we're selling to businesses like PayPal and Revolut and so on and so forth so that they already serve end users and they want to simplify it for their users to be able to pay globally, whether it's on-ramp or off-ramp, or you want to pay with crypto For instance, we have 700 million crypto owners. We have 400 million PayPal users. We have 100 million Amex cardholders. So if you're a merchant, you're accepting PayPal and Amex, you should accept crypto as well. So that's kind of the area that we are focused on. And the main problem, again, we are solving is the user experience to make it as easy as possible. So if you add all of these use cases, cross-border payment, B2B payment, consumer payments, like peer-to-peer payments, all sort of like type of money movement. It's a pretty large TAM from our perspective. The future of the economy will be tokenized and that tokenized economy is worth at least $100 trillion.
Gemma Allen
>> So talk about that world of B2B2C from the perspective of your own background, which is security, because it is somewhat of a different security and threat landscape, right? I don't know if you can say consumers or enterprises are looser with their security protocols. I guess we could argue that, but it's definitely a different user experience and user risk. How deeply is that factoring into the conversations with the B2B element of this? When you're working with companies like Revolut and PayPal, who owns that risk? And how is that new parameter being defined?
Bam Azizi
>> Yeah, we are trying to de-risk it as much as possible. At the end of the day, they own the relationship with the end users and they own the risk. Risk of any fraud or anything, but we will provide all sorts of information for the risk engine to make it as secure as possible. Again, my background is security and identity. So we build a platform that basically can pass any rigorous security testing. There is no such thing as bulletproof, but the best way to secure a system is to not store any information. So we're totally pass-through architecture. We're just passing information from the users to the customer, the business. We don't store any information. As a result of that, even if you get hacked, there is nothing to lose or there's nothing for hackers to get from us. And then we do follow all the best practices. And also we ask all our partners to follow the best practices. And we strongly believe if you really want to build a future payment network for the world, the first thing you need to do is security. So we don't call ourselves a payment company. We're security first. And everything else second. And because if you lose security, then you lose everything. But in addition to that, one interesting idea that we have and we're building is the Mesh identity that enables users to go securely from one platform, let's say PayPal, which is our customer, to let's say MetaMask, also our customer, and then their KYC information, their token information, their connections all of their information comes with them, and that's also decentralized and makes it super simple, but at the same time, very, very secure for the end users to move their ID or identity from one place to another without going through multiple authentication processes. So that's what we are bringing to the table. And I think if you look at, for instance, companies like Visa or Mastercard, when you're seeing their logo, you feel like, okay, this is a trusted platform. I can just swipe my card. And if something goes wrong, someone will make me whole. we want to build that image and that reputation for Mesh too.
Gemma Allen
>> So I want to go back to something you said there, which is the safest game to play here is not to store data, right? In the agentic world, what does that mean from the perspective of data retention though, from a context perspective? Because one thing we also hear over and over is that for agents to be more human-like, they need to have more of a unified sense of context, right? Which does involve a certain cache, if we're being clear about it. So how do those two kinds of debates play out?
Bam Azizi
>> Yeah, so that's where I'm super excited for the marriage of these two concepts: blockchain, decentralized storage, plus agent e-commerce. So having context doesn't mean you should lose security. That's the wrong idea. Having context without thinking about security is dangerous because your agent might share and overshare your information with somebody else. So building those guardrails is possible. Plus you want to add the decentralized aspect of it. Your agent can have access to your information, but only your agent can do that. It's your information, your data. You will authorize your agent to have access to it. You will authorize which company or which business or which other person or entity has access to your data. That doesn't mean your data should be insecure or should not follow best practices when it comes to security. So you can marry these two concepts with decentralized computation, decentralized storage. That's exactly what we are building. I think from Agenti Commerce perspective, what I'm excited about is not agent to human interaction. I'm more excited about agent to agent interaction. I think that would be the future. I would be happy to give you more information on that. Wow.
Gemma Allen
>> Well, it's certainly a very interesting debate and interesting space. And it sounds like a sound response. I want to move on to stablecoins. I mentioned to you before we went live here that we have a crypto trailblazer show. We talk a lot about folks in the industry. And I feel like stablecoins, the safe word, right? It's like a word folks use and they suddenly want to. And I say this jokingly, but it has this kind of resonance of maturity now, which maybe it didn't 5 years ago. And talk to me a little bit about your thesis. On stablecoins and this whole idea that it's not necessarily that crypto replaces banks, but it's that stablecoins have become a rail for moving dollars.
Bam Azizi
>> Yeah. So I think stablecoins are basically— they have— they're kind of one of the first tokenized assets. They have all the best of both worlds, right? So they are not volatile like other cryptocurrencies. But at the same time they're decentralized. They're like the U.S. dollar on steroids, right? So it basically solves the complexity of a very volatile asset like Bitcoin and others but they're on chain. But at the same time, it's instant, it's global, it's fast, it's cheap because it's decentralized and it can move from one place to another. In a blink of an eye. So I think the reason that stablecoin became the safe word is because it was the easiest one for regulators to look at because it had a lot of similarities to U.S. dollar or other stable currencies. And as a result of that, they were able to pass the GENIUS Act very quickly. And the next one is CLARITY Act. So GENIUS Act is mostly focused on stablecoin. CLARITY is just for broader assets or real-world assets and other types of tokens. So as a result of that, it becomes this regulatory safe haven that people can use blockchain only in that specific context, and it solves a lot of problems. So as they were saying, basically the killer use case for blockchain is stablecoin. And the clear use case for stablecoin is payment. So it solves a lot of problems. That's why you're hearing companies like Visa, Mastercard, and Stripe, they're actively investing heavily on stablecoin because it solves today's problem. But we want to kind of broaden that aspect to more companies, like companies that want to do trading, they want to work with other types of assets like equity, like trading and all sorts of things. That is where the GENIUS, the CLARITY Acts come into the picture and broaden that horizon. And I think that's the direction we are heading. But till then, yes, a stablecoin is the safe port.
Gemma Allen
>> So let's talk unit economics for a second, specifically as it relates to Mesh. You reached unicorn status in 2026, I believe. I hope I'm correct on that. So congratulations. Clearly there's a market appetite here for sure. Talk about your own business model. You say B2B to C. So again, it's like a license model, direct. Is it usage? How are you guys thinking about the future commercials of this? And also kind of a cheeky question, but I'm going to roll it in there. How sticky is this type of technology? Like, we know that you want to, you want to embed into big companies like Visa, like Revolut, etc. In this world, in this moment, How sticky is it versus 10 years ago when companies were doing this in the TradFi space?
Bam Azizi
>> I think it's pretty sticky because you will see more fragmentation, not less. That's kind of the reality of the world. And a company like Mesh that basically unfragment or consolidate the fragmented space has a lot of value to add. So once you plug into Mesh and it's extremely hard for you to pull the plug because if you pull the plug, then you have to basically build something similar. There is no such thing out there in the market. So we are the only solution doing that. So you have to build it yourself and nobody wants to do plumbing. But we are honored to be the chief plumbing officer and do all the plumbing and everyone is happy with this, with the service. I think that's kind of the main added value we have. We will lose our value if everything will be one currency, one chain, like something like North Korea, which we know never happens. And as a result of that, something like Mesh can abstract the complexity, has a tremendous amount of value compared to TradFi though. TradFi, when companies like Plaid and others came in, kind of solved similar type of issues. They were like the Web2 was there already for 20 years versus now that we're talking about stablecoin for the last couple of years. So we're at the beginning of the journey. So the more we move forward with agentic commerce and all sorts of things and tailwinds that happen in our favor, I think the future would be even more fragmented. And we have a long journey to go and a lot of products to build.
Gemma Allen
>> Wow. when I think of TradFi, I think, the obvious example, I guess, maybe is Stripe, right? Stripe-like infrastructure for digital assets. I hope that's a good takeaway from this conversation.
Bam Azizi
>> So yes.
Gemma Allen
>> Bam Azizi, thank you so much for joining us on NYSE Wired.
Bam Azizi
>> Thank you.
Gemma Allen
>> I'm Gemma Allen here at theCUBE Studio at the New York Stock Exchange. This is NYSE Wired's Mixture of Experts. Thanks for watching.








































 Gemma Allen