This discussion explores artificial intelligence, abbreviated AI, factories and the evolving role of data centers in technology investment. The conversation emphasizes how model scaling and rising capital expenditure reshape the technology stack and influence investment strategies across compute, chips, memory and optical networks.
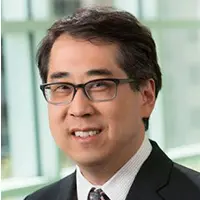
Tony Kim of BlackRock appears on theCUBE with hosts John Furrier and Dave Vellante. Kim leads the fundamental equities global technology team at BlackRock and they bring deep technology-focused investment expertise to the conversation.
Kim examines AI-driven shifts and explains that the market inverts as value and market capitalization migrate toward compute and infrastructure while models generate tokens with real cost of goods sold, abbreviated COGS. They argue that tracing token flow clarifies margin capture and that foundation-model spending cascades through hyperscalers, neo-clouds and inference clouds.
Hosts and analysts probe implications for software as a service, abbreviated SaaS, open-weight models strategic partnerships and where enduring enterprise moats form. The discussion highlights investment implications for data centers AI infrastructure semiconductors and cloud ecosystems, and it outlines factors to consider for institutional investors and technology leaders.
Forgot Password
Almost there!
We just sent you a verification email. Please verify your account to gain access to
theCUBE + NYSE Wired: AI Factories - Data Centers of the Future. If you don’t think you received an email check your
spam folder.
Sign in to AI Factories - Data Centers of the Future.
In order to sign in, enter the email address you used to registered for the event. Once completed, you will receive an email with a verification link. Open the link to automatically sign into the site.
Register for AI Factories - Data Centers of the Future
Please fill out the information below. You will receive an email with a verification link confirming your registration. Click the link to automatically sign into the site.
You’re almost there!
We just sent you a verification email. Please click the verification button in the email. Once your email address is verified, you will have full access to all event content for AI Factories - Data Centers of the Future.
I want my badge and interests to be visible to all attendees.
Checking this box will display your presense on the attendees list, view your profile and allow other attendees to contact you via 1-1 chat. Read the Privacy Policy. At any time, you can choose to disable this preference.
Select your Interests!
add
Upload your photo
Uploading..
OR
Connect via Twitter
Connect via Linkedin
EDIT PASSWORD
Share
Forgot Password
Almost there!
We just sent you a verification email. Please verify your account to gain access to
theCUBE + NYSE Wired: AI Factories - Data Centers of the Future. If you don’t think you received an email check your
spam folder.
Sign in to AI Factories - Data Centers of the Future.
In order to sign in, enter the email address you used to registered for the event. Once completed, you will receive an email with a verification link. Open the link to automatically sign into the site.
Sign in to gain access to theCUBE + NYSE Wired: AI Factories - Data Centers of the Future
Please sign in with LinkedIn to continue to theCUBE + NYSE Wired: AI Factories - Data Centers of the Future. Signing in with LinkedIn ensures a professional environment.
Are you sure you want to remove access rights for this user?
Details
Manage Access
email address
Community Invitation
Tony Kim, BlackRock
This discussion explores artificial intelligence, abbreviated AI, factories and the evolving role of data centers in technology investment. The conversation emphasizes how model scaling and rising capital expenditure reshape the technology stack and influence investment strategies across compute, chips, memory and optical networks.
Tony Kim of BlackRock appears on theCUBE with hosts John Furrier and Dave Vellante. Kim leads the fundamental equities global technology team at BlackRock and they bring deep technology-focused investment expertise to the conversation.
Kim examines AI-driven shifts and explains that the market inverts as value and market capitalization migrate toward compute and infrastructure while models generate tokens with real cost of goods sold, abbreviated COGS. They argue that tracing token flow clarifies margin capture and that foundation-model spending cascades through hyperscalers, neo-clouds and inference clouds.
Hosts and analysts probe implications for software as a service, abbreviated SaaS, open-weight models strategic partnerships and where enduring enterprise moats form. The discussion highlights investment implications for data centers AI infrastructure semiconductors and cloud ecosystems, and it outlines factors to consider for institutional investors and technology leaders.
Head of Fundamental Equities Global TechnologyBlackrock
search
Tony Kim
>> Palo Alto Studio Connection, Silicon Valley and Wall Street.
Dave Vellante
>> I'm John Furrier, co-host with Dave Vellante, my co-host. Welcome back to theCUBE's NYSE Wired Studio and our AI Factory series. I'm Dave Vellante. Tony Kim is a technology-focused investment manager. He's got a career that's spanning technology research, public equity investing, and investment banking at BlackRock. He leads the Fundamental Equities Global Technology team and also serves as lead portfolio manager of the BlackRock Technology Opportunities Fund. His investing focus is really centered on identifying global technology trends and, of course, companies and investment opportunities. Tony Kim, welcome to theCUBE. Good to see you.
Tony Kim
>> Good to see you.
Dave Vellante
>> Thanks for spending some time with us. All right. So let's lay out the landscape. What do you see in the landscape? Generally the investing landscape and of course, specifically, how's it looking to you from your vantage point?
Tony Kim
>> Well, it looks good to me. I'm not sure how the market feels about it. Yeah, I think we're seeing still early, early, early days. As you know, it's year 4 since ChatGPT, but the spending on one axis is capital spending. It's really last 2 years. It's really, really picked up. And it looks like this continues to the end of the decade. And then so that's the build-out phase. And now you're seeing the capabilities of the models starting to hit these exponential scaling capabilities. So capabilities are scaling faster than CapEx. And so it's an— that's an interesting dynamic. And so even though we're 4 years in, it feels like we're still at the early, early phases of this.
Dave Vellante
>> Yeah, and we're 4 years in. And then of course, that's since the AI shot heard around the world, but there was quite a bit of activity going on before then. So, you know, one could argue we're kind of 10 years into this, you know, sort of transformer, ChatGPT cycle. And so it was sort of gestating. And I think people sometimes, you know, forget about itand we can imagine where we're going to be 20 years in.
Tony Kim
>> Oh, yeah.
Dave Vellante
>> But the AI trade is obviously working for infrastructure. Do you see it broadening? Jensen talks a lot about, you know, applications and, you know, I'm going to talk to you about the SaaS-pocalypse and, you know, get your take there. But how is it broadening in Europe? Almost in some ways we were talking about optical. It seems to be deepening, you know, deeper down the stack versus up the stack. How do you see it?
Tony Kim
>> Yeah, the framing is right. It's compute and infra and then everything on top. Yeah. Atoms and electrons.
Dave Vellante
>> Right.
Tony Kim
>> And the infrastructure layer, there's going to be a continued sustained build. Because the model layer and above requires this computing layer. And what's interesting, though, is that every layer of the infra layer and then you go power chips, foundries, wafers, memory, optical, every layer, then there's tremendous competition.
Dave Vellante
>> Are you predominantly investing in that infra Well, yeah, yeah, yeah.
Tony Kim
>> So, yeah, the majority has gone to this layer as that's the market cap. So that's the market cap. And the market cap of tech I think is $60 trillion globally if you add up everything and probably 70-plus percent of it, if you— it depends on how you classify the Mag 7 infra companies, it's probably 70, 80% of the market cap has now gone down to this part of the stack. So the market cap has totally shifted prior to AI to now. But at that layer, at that infra layer, at this compute layer, there is a lot of competition in every single layer. And then above that stack, There is also a lot of, in fact, more changes going on there because what was perceived to be data apps services, those in many ways are those stacks are collapsing because the capabilities of the model are starting to take on many of those layers.
Dave Vellante
>> So I want to add, I want to come back to that. But as an investor, it's like A lot of things have inverted. Yes, CapEx heavy is now in favor. It seems like marginal economics at volume and ARR is out of favor. As an IT buyer, you used to want to lock in forward pricing. It's like the last thing you want to do now. I heard Jensen the other day say, you could sell the older GPUs for twice what you could last year. And in multiples, obviously they've expanded in infrastructure. You see, look at Dell's multiple now. And at the same time, I can't remember a time where the leader, in this case NVIDIA, has a lower PE than their competitors, which have a much, much higher multiple. Yes, it's like everything's inverted. How do you think about that? Why do you think that is and how do you think about that as an investor?
Tony Kim
>> So let's go back to the first— this shift of value and capitalization. The market, you know, that's not me. I'm saying the market has already spoken and said before the app layer had all the market cap and remember chips and hardware was a commodity, right?
Dave Vellante
>> Right.
Tony Kim
>> It was a commodity, a cyclical And the margins were lower and the margins were accrued to the app layer. And now it's reversed. That's also fundamentally, by the way, that's not true for Intel, right?
Dave Vellante
>> Intel was the dominant silicon player for years and they had the higher margins, much higher than AMD or NVIDIA companies.
Tony Kim
>> Yes. Yes. But as a class.
Dave Vellante
>> Yes. Okay.
Tony Kim
>> And now what you see is the market cap has flipped. And actually, the semiconductor sector is the most profitable sector in the world, actually in the world. No other industry has higher profitability than chips. And so what was perceived to be a commodity has flipped as the most profitable sector. What was the highest margin in software? There's a new physics of AI, right? You got to generate tokens.
Dave Vellante
>> Right.
Tony Kim
>> Tokens have real COGS to them. And so what was perceived to be asset-light, high, super high margin, long duration software, that's also changed. That idea has changed because you need to generate tokens and then you wrap apps around the token. And so this goes to this notion of what I think, as I look at it, token flow.
Dave Vellante
>> Follow the token.
Tony Kim
>> Follow the token. So you create tokens. You serve tokens and then you wrap your app around the token. And then at every layer of the stack around this token flow, there's margin. There's a battle for margin. There's a battle for margin. And then just going back to this, why has this inverted? That's a great, great, great coining of what has happened. There's been an inversion of many of our things that we thought about margins, about market cap, about durability, about moats. And so that's why you've seen so much money go into this compute layer, because that is the— you could call it the foundation of token factories, token generation. And then above that layer, now you're fighting for that super high margin area. But is that going to be instantiated in the model? Or will that be left for the app and service companies? And so there are battles going on at every layer. But in general, Marge, follow the token flow, then understand the margin structure of that token flow. And so then all your questions will be answered.
Dave Vellante
>> Yeah. So the token generators are getting the value. Yes, those token generators and those that are supporting the token generators, energy companies, data center, etc. At the macro, around 4% of company globally, companies revenue is spent on IT generally. We forecast that that's going to double or triple over the next decade. And basically you're going to shift This is essentially investment in labor to CapEx on tokens and token generation so that that thesis holds. And I want to ask you about when you go into the LLMs and you ask it a question, it'll write things like, well, it's not about the frontier models, it's about everything else. But of course, the news is all about the frontier models. Slow AI down. It's in the, you know, Dario and Sam are in the news every day. It's your earlier point. The LLMs, the frontier models, are gobbling up a lot of that functionality. So where do you land on the SaaS-pocalypse? We saw what happened over the last 6 months. Last week we saw Benioff and of course Dario, and he had this big pep rally. Out in San Francisco. And it seems like the world of deterministic and stochastic are coming together.
Tony Kim
>> That's exactly right.
Dave Vellante
>> But you would think that the LLM vendors, the frontier model vendors, are going to want to grab a lot of that stack. Do you see relationships like Anthropic and Salesforce as letting the fox in the henhouse, or do you see it as the way in which the leading SaaS companies are going to be able to compete for token value?
Tony Kim
>> So I think let's start with the Foundation Labs. I think you coined it well. It all starts with them, right? All eyes on them. Because in a way, just like in nature, there's a trophic cascade and the apex predator sets the stage for that whole ecosystem. Okay. So you have a few at the top.
Dave Vellante
>> Okay.
Tony Kim
>> Right. And their ambition, their spending, trickles down to hyperscale, to neo-clouds, inference clouds, compute layer. It just trickles down. So all action is on that. And then when you look, you also made a great point. You said IT is 4% of global GDP. Global GDP is like $120 trillion. I think it's roughly 60-40 between labor and capital. Yeah.
Dave Vellante
>> Okay. And that's going to flip as well.
Tony Kim
>> And so there are some reports by some of the labs that put out economic reports that suggest that ratio could flip from 60-40 labor to capital to capital-labor. But the GDP could accelerate. So you have like these different kinds of very— you have very different kinds of outcomes potentially at the pace at which AI happens. And that again goes back to what happens at the frontier. Okay. And then their spending and profitability also trickles down. OK, so that's one. Number two, then, this— I'm not going to comment on that specific relationship. But in general, what you pose is the central question that is the fox in the henhouse kind of analogy. But I would say that you have data above the compute layer. You have, let's call it context, enterprise context, proprietary, some, some data that is differentiation. You know, oftentimes some companies say that you're stealing my alpha, right? This is the data layer. There is an entire swath of applications, right? And then you have services. And then those three were very distinctly separate prior to AI. And then there was no LLM or no digital intelligence that wrapped it all together. And now what you're seeing is I think all of that is coming together. And so you are seeing potentially models, not only frontier proprietary models, but even open source Could it collapse the stack, take on, can it start building its own context? Can it consume all that data? Can it build the application, write code, build its own harness, and then with agents take on work? And so then this is where I don't think there's any clear endgame or idea of where it goes. And what's the value of the harness versus the value of the capabilities that are continually exponentially increasing on the models themselves? And so those to me, those worlds are colliding regardless of Fox in a henhouse or not. And it will be, it'll be a race to see where you can preserve your value.
Dave Vellante
>> So playing that back to you, another way of saying, I think what I just heard is that the software stack is getting upended by AI.
Tony Kim
>> It's getting consumed into the AI.
Dave Vellante
>> Right. And so when we went from on-prem to cloud, the whole software model changed everything. Yeah. Technology model, SaaS came out, the consumption pricing changed. And that seems to be happening again. The other piece of the software stack—
Tony Kim
>> and this is why they also— there's such a lot, so many proponents for open source, right? And open weight, because then you're not beholden to proprietary. You can control your own destiny somewhat by using open weight models.
Dave Vellante
>> So it gives me another thought. So, but the other piece of the software stack that is Now, radically changing is the interface. We've gone from command line to GUI, right, to point and click, web browser. And now, speaking. But so there's more.
Tony Kim
>> Well, not only speaking, you might not, in fact, eventually machine to machine.
Dave Vellante
>> Right, right.
Tony Kim
>> So you're not even involved with it.
Dave Vellante
>> Absolutely. So the whole client interface changes. But there are more kind of agent client-facing agent surfaces than there are fleas on a camel's back, we like to say. But there's presumably an interaction between that front-end client surface and the, what I would call the system of intelligence, that cognitive layer. And you call it context. Yeah. So you're going to, the back end is going to learn from the reasoning traces of the front end. Humans making exceptions or agents doing things right or wrong. So that closed loop regarding the open weight models and stealing of the alpha. Yeah, you could hire Alex Karp and Palantir to come in and do that. Kind of complicated, expensive. You could do it yourself with open weight models. The vast majority of enterprises, they want to— they can't figure it out. And this is why there's an argument that says if the LLM vendors make it really easy, they're going to consume a lot of that software stack. And so that would be the case for— and about buying Anthropic at the IPO, maybe wait. But nonetheless, they're going to grab more of that value. If they don't, by the way, how do they justify their valuations? So the question is, where might there be whitespace? It doesn't sound like you're ready to invest in that whitespace yet. You're still staying in the safe space, which is infrastructure. That's working well for you, I'm sure, but there's no evidence as to where that value is going to be up the stack, is there? pretty speculative.
Tony Kim
>> It's, let's call it, it's to be determined. Yeah, to be determined. But you're right, this context layer, this cognitive intelligence layer, that will be where enterprise value goes, right? It's that. And then you'll have full-stack LLMs, or you have open-source, open-weight models. And like you said, there'll be some that go fully outsourced, or you'll build it yourself, or you'll just hand it over, hand over the keys to a trusted— that's another big word that do you trust those entities? But that white space, as you call it, is— yeah, it's unclear how that all shakes out. But I think the course of direction, as I— if you were just to follow, if you believe, if you listen to, if we, if you believe in AGI and if you believe in these scaling laws and exponentially improving capabilities. What is the natural course of that path? And then you try to intercept that path and say, okay, who then has enduring moats in that world, right? But you're right, it's not obvious, and it's not obvious, but there are directional paths in which that is going, and I think I follow that. Again, that goes all the way back to so much focus on the Frontier Labs because they're pushing that frontier of capability.
Dave Vellante
>> And for them to capture more of that context. Yes, it's really not in their DNA, frankly. It's kind of not what they've done. They've got some quality people. So it's a combination probably of partnering maybe doing some inventing and doing some M&A. So that's the potential.
Tony Kim
>> I mean, you're seeing the partnering already for sure. You're starting to see them partnering. You have to. But you're right, it's not in their DNA. Right. They're labs, right. And dealing with Fortune 500, that's a very different world. So there is a partnership layer that needs to be there. And that's what we're seeing now. But in 10 years, what does it look like?
Dave Vellante
>> And you can see the labs struggling to go from sort of engineering to product development. Yes.
Tony Kim
>> Yes. You know, and that's a lot of the safety debate. It's around, is it an engineering or is it still the alignment issue at the research level or is it an engineering thing? And someone would suggest that you actually can engineer the safety.
Dave Vellante
>> Well, you were investing back in the dot-com days.
Tony Kim
>> Oh, yeah.
Dave Vellante
>> So these are fun times. You got to enjoy them while they last. So, Tony Kim, thanks so much for coming on theCUBE. Good to see you. Appreciate it. All right. Thank you for watching. This is Dave Vellante for theCUBE, NYSE Wired. Keep it right there. We'll be right back right after this short break.
>> Palo Alto Studio Connection, Silicon Valley and Wall Street.
Dave Vellante
>> I'm John Furrier, co-host with Dave Vellante, my co-host. Welcome back to theCUBE's NYSE Wired Studio and our AI Factory series. I'm Dave Vellante. Tony Kim is a technology-focused investment manager. He's got a career that's spanning technology research, public equity investing, and investment banking at BlackRock. He leads the Fundamental Equities Global Technology team and also serves as lead portfolio manager of the BlackRock Technology Opportunities Fund. His investing focus is really centered on identifying global technology trends and, of course, companies and investment opportunities. Tony Kim, welcome to theCUBE. Good to see you.
Tony Kim
>> Good to see you.
Dave Vellante
>> Thanks for spending some time with us. All right. So let's lay out the landscape. What do you see in the landscape? Generally the investing landscape and of course, specifically, how's it looking to you from your vantage point?
Tony Kim
>> Well, it looks good to me. I'm not sure how the market feels about it. Yeah, I think we're seeing still early, early, early days. As you know, it's year 4 since ChatGPT, but the spending on one axis is capital spending. It's really last 2 years. It's really, really picked up. And it looks like this continues to the end of the decade. And then so that's the build-out phase. And now you're seeing the capabilities of the models starting to hit these exponential scaling capabilities. So capabilities are scaling faster than CapEx. And so it's an— that's an interesting dynamic. And so even though we're 4 years in, it feels like we're still at the early, early phases of this.
Dave Vellante
>> Yeah, and we're 4 years in. And then of course, that's since the AI shot heard around the world, but there was quite a bit of activity going on before then. So, you know, one could argue we're kind of 10 years into this, you know, sort of transformer, ChatGPT cycle. And so it was sort of gestating. And I think people sometimes, you know, forget about itand we can imagine where we're going to be 20 years in.
Tony Kim
>> Oh, yeah.
Dave Vellante
>> But the AI trade is obviously working for infrastructure. Do you see it broadening? Jensen talks a lot about, you know, applications and, you know, I'm going to talk to you about the SaaS-pocalypse and, you know, get your take there. But how is it broadening in Europe? Almost in some ways we were talking about optical. It seems to be deepening, you know, deeper down the stack versus up the stack. How do you see it?
Tony Kim
>> Yeah, the framing is right. It's compute and infra and then everything on top. Yeah. Atoms and electrons.
Dave Vellante
>> Right.
Tony Kim
>> And the infrastructure layer, there's going to be a continued sustained build. Because the model layer and above requires this computing layer. And what's interesting, though, is that every layer of the infra layer and then you go power chips, foundries, wafers, memory, optical, every layer, then there's tremendous competition.
Dave Vellante
>> Are you predominantly investing in that infra Well, yeah, yeah, yeah.
Tony Kim
>> So, yeah, the majority has gone to this layer as that's the market cap. So that's the market cap. And the market cap of tech I think is $60 trillion globally if you add up everything and probably 70-plus percent of it, if you— it depends on how you classify the Mag 7 infra companies, it's probably 70, 80% of the market cap has now gone down to this part of the stack. So the market cap has totally shifted prior to AI to now. But at that layer, at that infra layer, at this compute layer, there is a lot of competition in every single layer. And then above that stack, There is also a lot of, in fact, more changes going on there because what was perceived to be data apps services, those in many ways are those stacks are collapsing because the capabilities of the model are starting to take on many of those layers.
Dave Vellante
>> So I want to add, I want to come back to that. But as an investor, it's like A lot of things have inverted. Yes, CapEx heavy is now in favor. It seems like marginal economics at volume and ARR is out of favor. As an IT buyer, you used to want to lock in forward pricing. It's like the last thing you want to do now. I heard Jensen the other day say, you could sell the older GPUs for twice what you could last year. And in multiples, obviously they've expanded in infrastructure. You see, look at Dell's multiple now. And at the same time, I can't remember a time where the leader, in this case NVIDIA, has a lower PE than their competitors, which have a much, much higher multiple. Yes, it's like everything's inverted. How do you think about that? Why do you think that is and how do you think about that as an investor?
Tony Kim
>> So let's go back to the first— this shift of value and capitalization. The market, you know, that's not me. I'm saying the market has already spoken and said before the app layer had all the market cap and remember chips and hardware was a commodity, right?
Dave Vellante
>> Right.
Tony Kim
>> It was a commodity, a cyclical And the margins were lower and the margins were accrued to the app layer. And now it's reversed. That's also fundamentally, by the way, that's not true for Intel, right?
Dave Vellante
>> Intel was the dominant silicon player for years and they had the higher margins, much higher than AMD or NVIDIA companies.
Tony Kim
>> Yes. Yes. But as a class.
Dave Vellante
>> Yes. Okay.
Tony Kim
>> And now what you see is the market cap has flipped. And actually, the semiconductor sector is the most profitable sector in the world, actually in the world. No other industry has higher profitability than chips. And so what was perceived to be a commodity has flipped as the most profitable sector. What was the highest margin in software? There's a new physics of AI, right? You got to generate tokens.
Dave Vellante
>> Right.
Tony Kim
>> Tokens have real COGS to them. And so what was perceived to be asset-light, high, super high margin, long duration software, that's also changed. That idea has changed because you need to generate tokens and then you wrap apps around the token. And so this goes to this notion of what I think, as I look at it, token flow.
Dave Vellante
>> Follow the token.
Tony Kim
>> Follow the token. So you create tokens. You serve tokens and then you wrap your app around the token. And then at every layer of the stack around this token flow, there's margin. There's a battle for margin. There's a battle for margin. And then just going back to this, why has this inverted? That's a great, great, great coining of what has happened. There's been an inversion of many of our things that we thought about margins, about market cap, about durability, about moats. And so that's why you've seen so much money go into this compute layer, because that is the— you could call it the foundation of token factories, token generation. And then above that layer, now you're fighting for that super high margin area. But is that going to be instantiated in the model? Or will that be left for the app and service companies? And so there are battles going on at every layer. But in general, Marge, follow the token flow, then understand the margin structure of that token flow. And so then all your questions will be answered.
Dave Vellante
>> Yeah. So the token generators are getting the value. Yes, those token generators and those that are supporting the token generators, energy companies, data center, etc. At the macro, around 4% of company globally, companies revenue is spent on IT generally. We forecast that that's going to double or triple over the next decade. And basically you're going to shift This is essentially investment in labor to CapEx on tokens and token generation so that that thesis holds. And I want to ask you about when you go into the LLMs and you ask it a question, it'll write things like, well, it's not about the frontier models, it's about everything else. But of course, the news is all about the frontier models. Slow AI down. It's in the, you know, Dario and Sam are in the news every day. It's your earlier point. The LLMs, the frontier models, are gobbling up a lot of that functionality. So where do you land on the SaaS-pocalypse? We saw what happened over the last 6 months. Last week we saw Benioff and of course Dario, and he had this big pep rally. Out in San Francisco. And it seems like the world of deterministic and stochastic are coming together.
Tony Kim
>> That's exactly right.
Dave Vellante
>> But you would think that the LLM vendors, the frontier model vendors, are going to want to grab a lot of that stack. Do you see relationships like Anthropic and Salesforce as letting the fox in the henhouse, or do you see it as the way in which the leading SaaS companies are going to be able to compete for token value?
Tony Kim
>> So I think let's start with the Foundation Labs. I think you coined it well. It all starts with them, right? All eyes on them. Because in a way, just like in nature, there's a trophic cascade and the apex predator sets the stage for that whole ecosystem. Okay. So you have a few at the top.
Dave Vellante
>> Okay.
Tony Kim
>> Right. And their ambition, their spending, trickles down to hyperscale, to neo-clouds, inference clouds, compute layer. It just trickles down. So all action is on that. And then when you look, you also made a great point. You said IT is 4% of global GDP. Global GDP is like $120 trillion. I think it's roughly 60-40 between labor and capital. Yeah.
Dave Vellante
>> Okay. And that's going to flip as well.
Tony Kim
>> And so there are some reports by some of the labs that put out economic reports that suggest that ratio could flip from 60-40 labor to capital to capital-labor. But the GDP could accelerate. So you have like these different kinds of very— you have very different kinds of outcomes potentially at the pace at which AI happens. And that again goes back to what happens at the frontier. Okay. And then their spending and profitability also trickles down. OK, so that's one. Number two, then, this— I'm not going to comment on that specific relationship. But in general, what you pose is the central question that is the fox in the henhouse kind of analogy. But I would say that you have data above the compute layer. You have, let's call it context, enterprise context, proprietary, some, some data that is differentiation. You know, oftentimes some companies say that you're stealing my alpha, right? This is the data layer. There is an entire swath of applications, right? And then you have services. And then those three were very distinctly separate prior to AI. And then there was no LLM or no digital intelligence that wrapped it all together. And now what you're seeing is I think all of that is coming together. And so you are seeing potentially models, not only frontier proprietary models, but even open source Could it collapse the stack, take on, can it start building its own context? Can it consume all that data? Can it build the application, write code, build its own harness, and then with agents take on work? And so then this is where I don't think there's any clear endgame or idea of where it goes. And what's the value of the harness versus the value of the capabilities that are continually exponentially increasing on the models themselves? And so those to me, those worlds are colliding regardless of Fox in a henhouse or not. And it will be, it'll be a race to see where you can preserve your value.
Dave Vellante
>> So playing that back to you, another way of saying, I think what I just heard is that the software stack is getting upended by AI.
Tony Kim
>> It's getting consumed into the AI.
Dave Vellante
>> Right. And so when we went from on-prem to cloud, the whole software model changed everything. Yeah. Technology model, SaaS came out, the consumption pricing changed. And that seems to be happening again. The other piece of the software stack—
Tony Kim
>> and this is why they also— there's such a lot, so many proponents for open source, right? And open weight, because then you're not beholden to proprietary. You can control your own destiny somewhat by using open weight models.
Dave Vellante
>> So it gives me another thought. So, but the other piece of the software stack that is Now, radically changing is the interface. We've gone from command line to GUI, right, to point and click, web browser. And now, speaking. But so there's more.
Tony Kim
>> Well, not only speaking, you might not, in fact, eventually machine to machine.
Dave Vellante
>> Right, right.
Tony Kim
>> So you're not even involved with it.
Dave Vellante
>> Absolutely. So the whole client interface changes. But there are more kind of agent client-facing agent surfaces than there are fleas on a camel's back, we like to say. But there's presumably an interaction between that front-end client surface and the, what I would call the system of intelligence, that cognitive layer. And you call it context. Yeah. So you're going to, the back end is going to learn from the reasoning traces of the front end. Humans making exceptions or agents doing things right or wrong. So that closed loop regarding the open weight models and stealing of the alpha. Yeah, you could hire Alex Karp and Palantir to come in and do that. Kind of complicated, expensive. You could do it yourself with open weight models. The vast majority of enterprises, they want to— they can't figure it out. And this is why there's an argument that says if the LLM vendors make it really easy, they're going to consume a lot of that software stack. And so that would be the case for— and about buying Anthropic at the IPO, maybe wait. But nonetheless, they're going to grab more of that value. If they don't, by the way, how do they justify their valuations? So the question is, where might there be whitespace? It doesn't sound like you're ready to invest in that whitespace yet. You're still staying in the safe space, which is infrastructure. That's working well for you, I'm sure, but there's no evidence as to where that value is going to be up the stack, is there? pretty speculative.
Tony Kim
>> It's, let's call it, it's to be determined. Yeah, to be determined. But you're right, this context layer, this cognitive intelligence layer, that will be where enterprise value goes, right? It's that. And then you'll have full-stack LLMs, or you have open-source, open-weight models. And like you said, there'll be some that go fully outsourced, or you'll build it yourself, or you'll just hand it over, hand over the keys to a trusted— that's another big word that do you trust those entities? But that white space, as you call it, is— yeah, it's unclear how that all shakes out. But I think the course of direction, as I— if you were just to follow, if you believe, if you listen to, if we, if you believe in AGI and if you believe in these scaling laws and exponentially improving capabilities. What is the natural course of that path? And then you try to intercept that path and say, okay, who then has enduring moats in that world, right? But you're right, it's not obvious, and it's not obvious, but there are directional paths in which that is going, and I think I follow that. Again, that goes all the way back to so much focus on the Frontier Labs because they're pushing that frontier of capability.
Dave Vellante
>> And for them to capture more of that context. Yes, it's really not in their DNA, frankly. It's kind of not what they've done. They've got some quality people. So it's a combination probably of partnering maybe doing some inventing and doing some M&A. So that's the potential.
Tony Kim
>> I mean, you're seeing the partnering already for sure. You're starting to see them partnering. You have to. But you're right, it's not in their DNA. Right. They're labs, right. And dealing with Fortune 500, that's a very different world. So there is a partnership layer that needs to be there. And that's what we're seeing now. But in 10 years, what does it look like?
Dave Vellante
>> And you can see the labs struggling to go from sort of engineering to product development. Yes.
Tony Kim
>> Yes. You know, and that's a lot of the safety debate. It's around, is it an engineering or is it still the alignment issue at the research level or is it an engineering thing? And someone would suggest that you actually can engineer the safety.
Dave Vellante
>> Well, you were investing back in the dot-com days.
Tony Kim
>> Oh, yeah.
Dave Vellante
>> So these are fun times. You got to enjoy them while they last. So, Tony Kim, thanks so much for coming on theCUBE. Good to see you. Appreciate it. All right. Thank you for watching. This is Dave Vellante for theCUBE, NYSE Wired. Keep it right there. We'll be right back right after this short break.



























 Dave Vellante